Chapter 7 Bankruptcy

How This Article Was Reviewed▾
How We Review This Educational Content▾
Why You Can Trust This Page▾
Two people with the same amount of debt can have very different experiences with Chapter 7 bankruptcy. The reason? How much you owe is only part of the picture. Chapter 7 can eliminate many debts, like credit card balances or medical bills, often within a few months. That’s part of why it’s the most popular chapter of bankruptcy. But your income, the types of debt you have, and the property you own all play a role in whether it’s the right option for you.
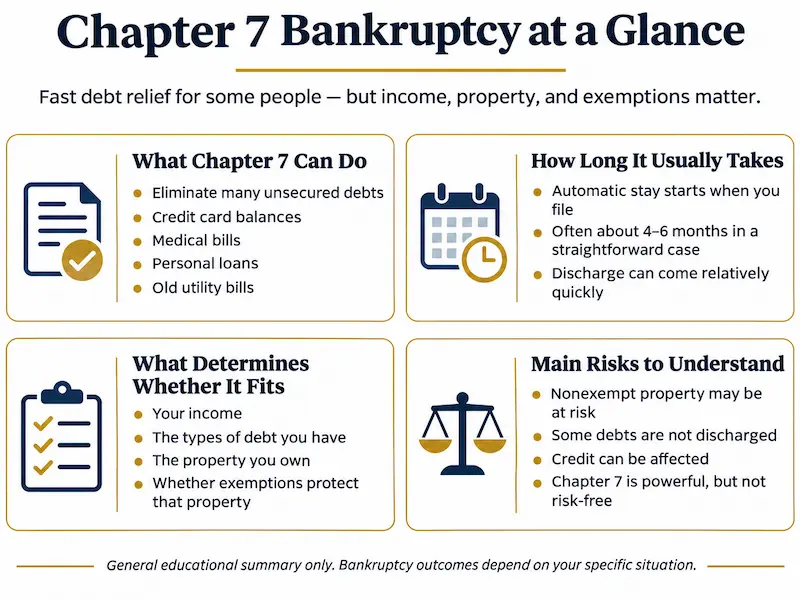
Chapter 7 bankruptcy has some drawbacks worth considering before you decide whether it is right for you. Because it’s a form of “liquidation bankruptcy,” you could risk losing some of your property, like your home and vehicle, to repay creditors if those assets are not protected by bankruptcy exemptions. Chapter 7 can also impact your credit score, so it’s helpful to understand the long-term repercussions and how to rebuild credit after your case is closed.
How Does Chapter 7 Bankruptcy Work?
A Chapter 7 case begins when you file a petition with the court. After filing, an automatic stay generally takes effect right away. This legal protection, established under 11 U.S.C. § 362, can instantly stop or pause most debt collection efforts, including collection calls, lawsuits, wage garnishments, repossessions, and foreclosures.
After your case is filed, a Chapter 7 trustee is assigned to your case. The trustee reviews your financial paperwork, looks over your assets and exemptions, and conducts the 341 meeting of creditors, where you’ll answer questions under oath about your finances. The trustee also determines whether you have any nonexempt assets that aren't protected by bankruptcy exemptions. These assets can be sold or settled for the benefit of creditors.
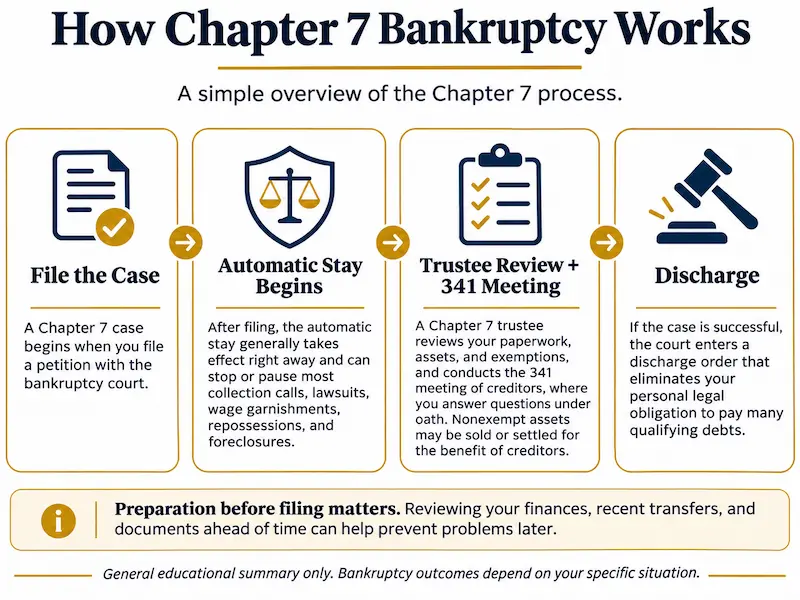
If your case is successful, you’ll receive a discharge order from the court, which eliminates your personal legal obligation to pay many of your qualifying debts.
This is just a brief overview of the process. For a closer look at what happens before, during, and after filing, see our 8 Steps to File for Chapter 7 Bankruptcy below.
What Debts Does Chapter 7 Bankruptcy Discharge?
Chapter 7 can eliminate many debts you had before filing for bankruptcy under 11 U.S.C. § 727(b). This includes most unsecured debts, such as credit cards, medical bills, personal loans, and old utility bills. These are debts that aren’t legally tied to specific property a creditor can take back if you do not pay them.
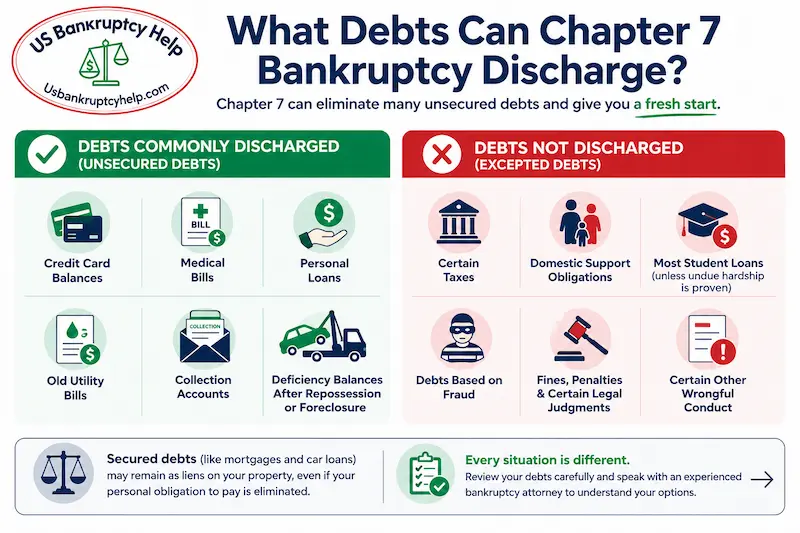
Secured debts work differently because they’re connected to property. A vehicle loan, for example, is secured by a car, truck, or van. Chapter 7 can stop you from having to pay back the loan, but it doesn’t take away the lender’s legal right to the property. If you cannot afford the loan or don’t want to keep your vehicle, you may be able to surrender it and have the remaining loan amount that qualifies for discharge removed. This same principle could potentially be applied to a house, boat, or ATV.
Examples of Debts Commonly Discharged in Chapter 7
Common examples of debts that may be discharged in Chapter 7 include:
- Credit card balances
- Medical bills
- Personal loans
- Old utility bills
- Collection accounts
- Deficiency balances after repossession or foreclosure
What Debts Stay With You, Even After Chapter 7 Bankruptcy?
Not every debt is discharged in Chapter 7 bankruptcy. Examples of debts excepted from discharge under 11 U.S.C. § 523 include:
- Child support and Alimony obligations
- Most student loans, unless undue hardship is proven
- Certain tax debts, including many recent income taxes and some penalties
- Debts based on fraud or false pretenses
- Debts for willful and malicious injury to another person or property
- Certain fines, penalties, or restitution obligations
Chapter 7 vs. Chapter 13 Bankruptcy
Chapter 7 isn’t always the best option. Depending on your specific case, Chapter 13 bankruptcy may be a better fit. While Chapter 7 allows you to quickly eliminate qualifying debt, filing for Chapter 13 can give you more time to catch up on a mortgage, protect property, deal with nonexempt equity, or restructure certain secured debts.
The table below allows you to compare Chapter 7 and Chapter 13 to see how they differ in terms of their purposes, who qualifies, how long each process takes, and other important factors.
| Issue | Chapter 7 | Chapter 13 |
|---|---|---|
| Main Purpose | Discharge qualifying debts faster. | Use a court-approved repayment plan to catch up, reorganize, or protect property. |
| Who Can File | Individuals, married couples, corporations, and partnerships. Corporations and partnerships do not receive a Chapter 7 discharge. (USC § 727(a)(1)) | Individuals and married couples. Business entities cannot file Chapter 13. |
| Eligibility Rules | Most consumer filers must pass the means test or qualify for an exception. (See below for more details about the means test.) | The filer must have regular income and be able to make the required plan payments. |
| Debt Limits | Chapter 7 does not have the same debt-limit structure as Chapter 13. | Chapter 13 has debt limits under 11 U.S.C. § 109. |
| Typical Case Length | Often about 4 to 6 months in a straightforward case. | Usually 3 to 5 years, depending on income, plan requirements, and case facts. |
| What Happens to Property | Property protected by exemptions is kept. Nonexempt property may be sold by the trustee. | The filer usually keeps property, but nonexempt equity may increase the plan payment. |
| Mortgage or Car Loan Arrears | Chapter 7 does not create a long-term plan to catch up on missed payments. | Chapter 13 may allow missed payments to be caught up over time. |
| Biggest Advantage | Faster relief and a discharge of many qualifying debts without a multi-year repayment plan. | More time and flexibility to protect property, catch up on important payments, and deal with secured debts. |
Legal Sources: The law behind Chapter 7 and Chapter 13 can be found in 11 U.S. Code Chapter 7 and 11 U.S. Code Chapter 13.
Chapter 7 vs. Chapter 13 Decision Tool
There are lots of articles on the web about the differences between chapter 7 and chapter 13. We know it's hard to keep up with all this information, so we made the Chapter 7 vs Chapter 13 Decision Tool for people to use to help them decide between these two chapters.
Simply enter your information into the fields below, follow the prompts, and hit "next". At the end you will get a recommendation based on your input. You may print or save a PDF of this estimate for your records. We do not store any of this info and none of your personal information like name, address and email are required to fill out the form and get a result.
Chapter 7 vs Chapter 13 Decision Tool
Answer a few questions to get an educational estimate of which bankruptcy chapter may fit your situation.
Step 1 of 2
Window 1 of 2: Income Snapshot
This tool is for educational purposes only and is not legal advice.
4 Factors That May Make Chapter 7 Bankruptcy a Better Option
No single factor determines whether Chapter 7 is right for you. Your debts, income, property, and recent financial activity all matter. Here are four things to consider before deciding whether to file.
Most of Your Debt Qualifies for Discharge
Chapter 7 may be a good option if most of what you owe is credit card debt, medical bills, or personal loans. It may also be a good option if you need to give up property that you can no longer afford and discharge your personal liability on the underlying debt.
Your Property Is Protected by Exemptions
Bankruptcy exemptions determine which assets you can keep. The exemptions that you have available to you depend on state and federal law. Most states have a homestead exemption, for example, that allows Chapter 7 filers to protect equity in their home.
You Can’t Afford a Repayment Plan
If there isn't any room in your budget for a monthly bankruptcy plan payment after covering necessities like mortgage/rent, groceries, and basic living expenses, Chapter 7 usually makes more sense than Chapter 13.
You Don't Have Recent Financial Activity That Could Complicate Your Case
In Chapter 7, you have to share details about your financial situation. For example, in the Statement of Financial Affairs you usually have to disclose if you sold any property or transferred any property within a certain time period before filing.
How Do You Qualify for Chapter 7 Bankruptcy?
Your income is one of the main factors that determine whether Chapter 7 is an option for you. For most people, the first step is to compare their income with the median income in their state.
Income and the Chapter 7 Means Test
The Chapter 7 means test looks at your income and certain allowable expenses to help determine whether your income qualifies for Chapter 7 bankruptcy. A good starting point is to compare your income with the median income for your state and household size. If what you make falls below the median, it will generally meet the requirements to qualify for a discharge under Chapter 7. However, if your income is higher, your income may still qualify by passing the means test or qualifying under an exception.
Not sure where you stand? Our Chapter 7 Means Test Calculator can give you a detailed estimate based on your income and expenses. This tool isn't meant to replace solid legal advice, but it can be a great starting point. It may be useful to have paycheck stubs on hand to help you determine income amounts. You can print and/or save your results. We do not save any of the info you enter and you are not required to enter any personal information into the tool.
Chapter 7 Means Test Calculator
Compare income with the state median, then estimate allowable expenses and the means-test result if income is above median.
Chapter 7 Means Test Calculator
Compare income with the state median, then estimate allowable expenses and the means-test result if income is above median.
Educational estimate only. This Chapter 7 means test calculator is not legal advice, does not create an attorney-client relationship, and cannot account for every legal nuance. Attorney review may still be necessary.
Filing-date tables determine the income, county, transportation, and age-based health allowances. This estimate uses the people and deduction amounts you enter. It does not resolve household or non-filing spouse rules, a marital adjustment, special circumstances, or every uncommon deduction. Individual filers are limited to one vehicle in this estimator. Ask your attorney how local practice applies to additional vehicles. A result does not determine eligibility for chapter 7 or guarantee a discharge. Review your entries using USTP resources and Official Form 122A-2.
Step 1: Initial Screening
Include the people counted in your household for the means test, not just the people filing. Household and non-filing spouse rules can depend on your circumstances and local practice. Confirm this count with your attorney.
This may differ from household size. Line 5 asks for people who could be claimed as tax exemptions plus additional dependents you support. Have your attorney confirm who counts, particularly a spouse who is not filing.
Consumer debts are usually personal, family, or household debts.
Enter your actual or planned filing date. Historical tables are included from November 1, 2025. Tables were last reviewed October 7, 2026; later dates remain available as provisional planning estimates. The income period is the six complete calendar months before filing.
Select a supported filing date to load its tables. Presumption thresholds effective April 1, 2025: $10,275 and $17,150 (60-month).
Why Are Bankruptcy Exemptions Important in Chapter 7 Bankruptcy?
Bankruptcy exemptions determine what property you can protect. This is a critical part of Chapter 7 because the trustee is allowed to review your assets and, in some cases, sell property that is not protected by an exemption.
Bankruptcy is a federal court process, but exemption rules vary by state. The exemptions available to you usually depend on where you live and how long you have lived there. For example, if you've moved from another state within the last two years, you may not be able to use the bankruptcy exemptions of the state where you currently live. Our Bankruptcy Exemption Law Finder Tool can walk you through your residency history and give you an educational estimate of which state's exemption laws likely would apply in your case.
8 Steps to File for Chapter 7 Bankruptcy
Here’s what you can generally expect, from preparing your case to receiving a Chapter 7 discharge:
Review Your Financial Situation Before Filing
Before filing, always review your debts, income, property, exemptions, and recent financial activity. This is the time to identify issues such as property that may not be exempt, recent transfers or payments to friends or family, large credit card charges, or secured debts you may no longer want to keep. Take this time to understand the potential benefits and risks of Chapter 7 before you file.
Complete the Required Credit Counseling Course
You have to complete an approved credit counseling course within the 180 days before filing your bankruptcy case. This is a separate requirement from the debtor education course which is completed after the case is filed.
Gather Your Documents and Prepare the Bankruptcy Forms
Chapter 7 requires you to provide detailed information about your income, expenses, debts, property, creditors, exemptions, and recent financial history. You will probably need to provide pay stubs, tax returns, and bank statements to your trustee. Also be prepared to produce mortgage and vehicle loan information, and possibly records showing the value of your property. Your bankruptcy petition is signed under penalty of perjury, so it should be true, accurate, and complete.
File Your Chapter 7 Case With the Bankruptcy Court
When you file your bankruptcy petition, that is when your Chapter 7 case officially begins. You have to pay a filing fee unless you apply and qualify to pay the fee in installments or, in some cases, receive a fee waiver. Filing the case also triggers the automatic stay, which generally stops or pauses many creditor activities (like collections, garnishments, and collection lawsuits) while the bankruptcy case is pending.
Provide Required Documents to the Chapter 7 Trustee
A trustee will be assigned to your case. You’ll most likely be required to provide them with certain documents, including proof of income (like pay stubs and profit-and-loss statements), bank statements, your most recent tax returns, and any additional documents the trustee requests.
Attend the “341 Meeting” of Creditors
At this required meeting, commonly called the "341 meeting," the trustee will ask you questions under oath about your finances and bankruptcy paperwork. This isn't a court hearing, and the trustee isn't a judge. Creditors may attend and ask questions, although they rarely do.
Complete the Debtor Education Course
After filing, you have to complete a separate debtor education or personal financial management course before you can receive your Chapter 7 discharge. The required certificate must be filed with the court.
Receive the Chapter 7 Discharge
If you complete the required steps and there are no issues preventing discharge, the bankruptcy court generally enters a discharge order that eliminates your personal liability for the qualifying debts we discussed above.
How Chapter 7 Affects Your Credit
Generally, the fact that you filed Chapter 7 bankruptcy can remain on your credit report for up to 10 years from the filing date. That doesn't mean you are locked out of credit for 10 years. It just means future lenders may take the bankruptcy into consideration when deciding whether to approve credit.
What you do after your bankruptcy can make a real difference in rebuilding your credit. Not being late on payments, keeping your balances manageable, using new credit responsibly, and monitoring your credit reports can all help you rebuild over time.
How Much Does It Cost to File Chapter 7 Bankruptcy?
Court Filing Fee & Courses
At the moment, the Chapter 7 court filing fee is $338. If you can't pay the full fee at once, the court may allow you to pay it in installments. You can also obtain a fee waiver, but this is only for qualifying low-income filers. You may also have to pay for the mandatory pre-filing credit counseling course and the post-filing debtor education course required to receive a discharge. The cost of these courses is usually relatively small.
Chapter 7 Attorney Fees
There is no standard attorney fee. The attorney fee varies by case complexity and location. Attorneys may also add additional costs for things like credit reports.
Chapter 7 Bankruptcy FAQs
Here are answers to some common questions people have about Chapter 7 bankruptcy:
What Happens to My Home or Car if I File Chapter 7?
If you have a mortgage or car loan, the lender has a legal claim to that property until the loan is paid off. This is called secured debt because the property serves as collateral for the loan. Chapter 7 can remove your liability for qualifying secured debts, but it generally cannot eliminate the lender’s right to take the property if you stop making payments. Depending on your circumstances, you may be able to keep your home or vehicle, or you may choose to give it up (known as surrendering the property). If you surrender the property, any remaining qualifying loan balance can generally be discharged.
Other options may include reaffirming the debt (agreeing to remain personally responsible for the loan) or, in certain cases, redeeming personal property by paying its current value in a lump sum. Bankruptcy exemptions also play a role in determining what property you can keep.
How Long Does Chapter 7 Take?
A Chapter 7 case that is "straightforward" often takes about four months from filing to discharge. This timeline can vary depending on the case. A case could remain open longer if the trustee administers nonexempt property, investigates an issue, or deals with other issues that have to be resolved before the case can be closed.
Can I File Chapter 7 Without a Lawyer?
Yes. Individuals are allowed to file Chapter 7 bankruptcy without a lawyer. This type of filing is called pro se. Bankruptcy is complex, however, and involves specific law, court rules, exemptions, financial disclosures, and deadlines. A mistake in your filing can affect your assets or your ability to receive a discharge. If you have property you want to protect, financial transactions, significant secured debt, or other complications, it may be worth having a bankruptcy lawyer review your situation before you file.
How Much Debt Is Required to File Chapter 7?
There are no debt limits in Chapter 7 bankruptcy. Chapter 7 does not have a minimum amount of debt required to file nor does it have a debt ceiling.
How Often Can I File Chapter 7?
There isn't necessarily a limit on the number of bankruptcy cases you can file, but there are limits on how often you can receive a discharge. If you previously received a Chapter 7 discharge, you must wait eight years from the filing date of that case before you can get a discharge in another Chapter 7 case under 11 U.S.C. § 727(a)(8). If your previous bankruptcy case was a Chapter 13 case, or didn't result in a discharge being entered, different timing rules can apply.
How Long Will Chapter 7 Stay on Your Credit Report?
Chapter 7 bankruptcy can remain on your credit report for 10 years.
Legal Disclaimer: USBankruptcyHelp.com is not a law firm and does not provide legal or financial advice. Nothing on this website should be considered legal or financial advice. The contents of this Chapter 7 guide are for educational purposes only and are not legal or financial advice. Choosing to file Chapter 7 bankruptcy depends on your unique and specific financial situation and is a decision that may require careful consideration.
Related Bankruptcy Questions
Explore Bankruptcy Help by State
Browse our state guides to learn exemptions, means test rules, costs, and local procedures. Use these links to jump between states and compare your options.
- Arizona
- California
- Colorado
- Florida
- Georgia
- Illinois
- Indiana
- Maryland
- Michigan
- Nevada
- New York
- North Carolina
- Ohio
- Oregon
- Pennsylvania
- Tennessee
- Texas
- Virginia
- Wisconsin