Chapter 7 vs Chapter 13 Bankruptcy: What's the Difference?

How This Article Was Reviewed▾
How We Review This Educational Content▾
Why You Can Trust This Page▾
People thinking about filing bankruptcy are usually considering either chapter 7 bankruptcy or chapter 13 bankruptcy. The chapter that makes the most sense for you will depend on your specific financial picture and goals.
Income and assets are usually the two main factors that will influence your decision. Income is important because bankruptcy law requires income calculations that can affect Chapter 13 plan requirements and Chapter 7 eligibility.
In a consumer Chapter 7 case, the means test can determine whether a presumption of abuse arises. Being over your jurisdiction's median income level does not automatically disqualify you from Chapter 7 because additional means test calculations can still show that no presumption of abuse arises. Also, even when a presumption arises bankruptcy law provides some circumstances where it can be rebutted. In Chapter 13 cases, income calculations usually affect the length of the Chapter 13 plan and how much disposable income may need to be paid to certain creditors.
Chapter 7 vs. Chapter 13 at a Glance
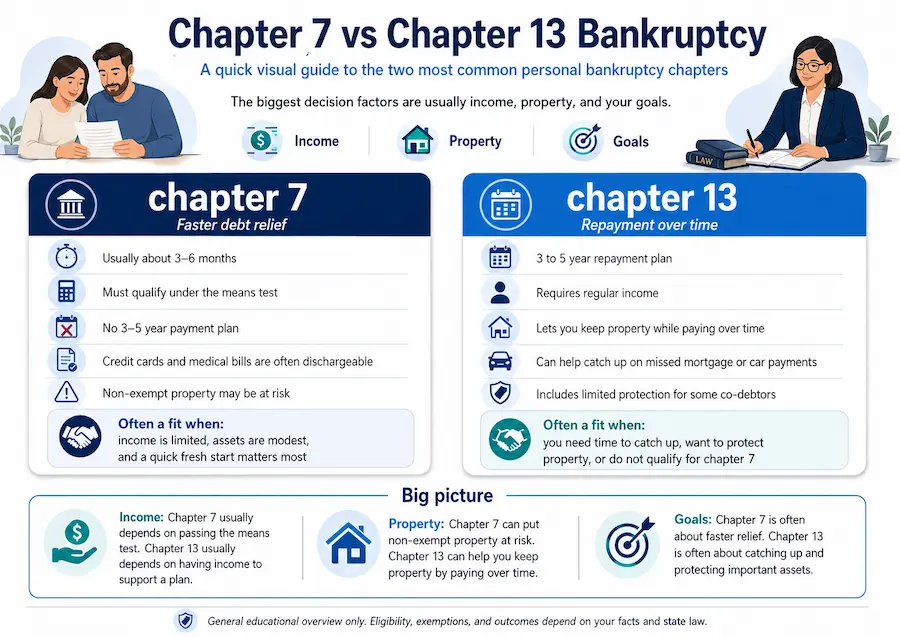
Chapter 7 is usually faster and is commonly used to discharge qualifying debts without a multi-year repayment plan, but nonexempt property can be at risk.
Chapter 13 involves a three- to five-year payment plan and can provide additional tools to catch up on secured debt, pay priority debts such as certain taxes and domestic support obligations, protect nonexempt property, and reorganize certain obligations such as vehicle loans.
The assets you own are also an important consideration because property that is not protected by a bankruptcy exemption, or is not fully protected by a bankruptcy exemption, could be at risk in Chapter 7. Chapter 13, on the other hand, may allow you to keep property that would otherwise not be protected in Chapter 7, although nonexempt equity could increase the amount that must be paid to unsecured creditors through the Chapter 13 plan.
Those who qualify for chapter 7 may also be able to file for chapter 13 if their income is enough to make Chapter 13 plan payments. Chapter 7 qualifiers may opt for Chapter 13 for several reasons (which we will discuss below).
Legal Sources: The law behind chapter 7 and chapter 13 is found in 11 U.S. Code Chapter 7 and 11 U.S. Code Chapter 13.
Chapter 7 vs Chapter 13 Decision Tool
We made the chapter 7 vs chapter 13 decision tool below to help you on your journey to finding the best solution for your specific situation. This tool is free to the public. We do not ask for any contact information. You won't be asked for email, phone number, etc. at the end of the form.
Simply answer the questions below about income, debt and your goals. At the end you will get a summary of which chapter might be a better fit based on your input, broken down into three categories (income, your goals, and your assets). You can save and print your results if you want to keep them for your records, or if you want to share the info with a bankruptcy lawyer.
Please remember that the chapter 7 vs chapter 13 decision tool is an educational tool. You shouldn't rely on it as any sort of legal advice.
Chapter 7 vs Chapter 13 Decision Tool
Answer a few questions to get an educational estimate of which bankruptcy chapter may fit your situation.
Step 1 of 2
Window 1 of 2: Income Snapshot
ZIP lookup is optional and used as a quick state check.
Chapter 7 vs Chapter 13 Bankruptcy
The table highlights some of the main differences between chapter 7 and chapter 13 bankruptcy for individuals and couples (joint filers).
| Category | Chapter 7 | Chapter 13 |
|---|---|---|
| Typical Timeline | Discharge usually occurs approximately 4 months after filing (varies by case) | Discharge entered after 3 to 5 year payment plan |
| Eligibility Gate | Most filers must satisfy the Chapter 7 means test rules or qualify under an exception. | Must have regular income and have less than $526,700 in unsecured debt and less than $1,580,125 in secured debt according to the current Chapter 13 debt limits. |
| Unsecured Debt (Credit Cards, Medical Bills) | Qualifying unsecured debts can be discharged without a payment plan. | Qualifying unsecured debts receive treatment through the Chapter 13 plan and remaining dischargeable amounts can be discharged after successful completion of the plan. |
| Mortgage Arrears | Chapter 7 does not provide a plan for curing mortgage arrears. | Mortgage arrears can generally be cured through the plan. |
| Car Loans | Keeping a financed vehicle may involve remaining current and, depending on the circumstances, reaffirming the debt or redeeming the vehicle. | Vehicle arrears can be cured. In some cases, loan terms may be adjusted and/or "crammed down" . |
| Non-Exempt Property | Property without an exemption is subject to sale or settlement. | The filer can generally keep the property, but equity without an exemption may increase the amount that must be paid to unsecured creditors through the Chapter 13 plan. |
| Co-Signer Protection | Does not provide ongoing protection for non-filing co-signers | Includes a limited co-debtor stay for certain consumer debts during the case |
| Credit Reporting | Bankruptcy notation may remain on credit reports for up to 10 years. | Bankruptcy notation may remain on credit reports for up to 7 years. |
When Chapter 7 Could Be a Better Option Than Chapter 13
Below are examples of scenarios where chapter 7 might be a better option than chapter 13:
You Do Not Have Enough Income to Support a Repayment Plan
Chapter 7 may make more sense when there is not enough income left over each month to fund a Chapter 13 plan. Some people are already stretched thin trying to cover housing, food, utilities, transportation, and other necessary expenses. When the budget does not realistically allow for a monthly plan payment, chapter 7 may be the more practical path.
You Have Limited Property and Mostly Unsecured Debt
If you don't have a lot of property and most of your debt is the type of debt that could be discharged in Chapter 7, Chapter 7 may be a stronger option for you. For example, if you rent your home, own ordinary household belongings, drive an old vehicle with little equity, and are struggling with credit cards, medical bills, personal loans, or other unsecured debt you may find that Chapter 7 could give you more meaningful relief and avoid a three to five year payment plan.
You Want Relief From Debt Sooner
Chapter 7 may be the better choice when the priority is to eliminate unsecured debt in a shorter amount of time. Someone dealing with heavy credit card balances, medical bills, or older personal loans may prefer chapter 7 because the path to discharge is usually much quicker than it is in chapter 13.
When Chapter 13 Could Be a Better Option Than Chapter 7
Below are a few scenarios where chapter 13 could be a better option than chapter 7:
You Need to Catch Up on Missed Mortgage Payments
If you are behind on your mortgage payments for your primary residence, want to keep that home and need a way to catch up the mortgage arrears, chapter 13 provides a path where you can pay them back through the 3 to 5 year plan. Chapter 13 can also be used to stop a foreclosure if those house payments have gotten too far behind and your lender is taking foreclosure actions.
The usual action taken here would be to file the case before the foreclosure date, properly give notice of the chapter 13 case to the mortgage lender, and file a Chapter 13 plan that provides the mortgage lender with the missed mortgage payments. Usually you will also have to remain current with on-going mortgage payments while you are in your Chapter 13 plan for this to work.
You Need to Catch Up on Missed Car Payments
If you are behind on your vehicle's payments and need a way to catch them up, you can use your Chapter 13 plan payments to do that.
You Need to Protect Property That Might Be at Risk in Chapter 7
If you have property that is not exempt which would be at risk for sale in a chapter 7 liquidation, you could file a chapter 13 and provide payment to creditors for that nonexempt asset in your Chapter 13 plan.
Example. Assume you have a recreational vehicle like an RV or boat that has no exemption. In a Chapter 7, the trustee could sell this asset and use the proceeds to pay creditors. In a Chapter 13, you could generally keep the asset, but your plan would generally have to provide unsecured creditors at least as much as they would have received in a hypothetical Chapter 7 liquidation under 11 U.S.C. § 1325(a)(4).
You Want to Protect a Co-Debtor
If you have a co-debtor, like a friend, family member, or former spouse who is also obligated on a debt, chapter 13 can protect them from collection actions for some consumer debts during the case through a limited co-debtor stay under 11 U.S.C. § 1301. Chapter 7 does not provide this protection.
Chapter 7 vs. Chapter 13 Bankruptcy FAQs
If you're trying to choose between Chapter 7 and Chapter 13, you may have questions about timing, cost, eligibility, and how each chapter handles certain debts. Here are answers to some common questions.
Can I File Chapter 7 Before 8 Years?
You may be able to file another Chapter 7 bankruptcy case before eight years have passed, but that doesn't mean you can receive another Chapter 7 discharge. If you previously received a Chapter 7 discharge, 11 U.S.C. § 727(a)(8) generally prohibits another Chapter 7 discharge when a new case is filed within eight years of the filing date of the previous Chapter 7 case. The timing rules are different if your previous discharge was under Chapter 13 or if your previous case did not result in a discharge. In some situations, Chapter 13 can be an option if you have to file before you are eligible for another Chapter 7 discharge.
Can You Declare Bankruptcy on Student Loans?
Yes. Student loans can be included in a bankruptcy case, but you may not be able to discharge them. Under 11 U.S.C. § 523(a)(8), qualifying student loan debt generally requires a separate determination that repaying the student loans would impose an undue hardship. You can attempt to show undue hardship and seek student loan discharge in Chapter 7 and Chapter 13. If student loans are a major part of your debt, read our complete guide on student loan discharge in bankruptcy.
How Much Debt Do You Need to File Chapter 7?
There isn't a minimum amount of debt you must have to file Chapter 7 bankruptcy, and Chapter 7 doesn't have debt limits like Chapter 13. Whether or not Chapter 7 is right for you depends on more than the total amount of debt you owe. You probably also need to consider your income, the types of debt you have, your property and the exemptions available to protect that property.
How Long Does Bankruptcy Take?
This depends on the chapter you file and your situation. In a straightforward Chapter 7 case, discharge can be entered in about four months after filing, but a case could remain open longer if there are assets or other issues that need to be resolved. Chapter 13 is usually much longer than Chapter 7 because it involves a 3 to 5 year repayment plan.
How Much Does a Lawyer Charge for Chapter 7?
There isn't a standard attorney fee for a Chapter 7 bankruptcy. Fees can vary depending on where you live, how complex your case is, the amount and type of debt you have, the amount and type of property you own, and your financial history.
How Much Does Filing Chapter 13 Cost?
The current filing fee for filing a Chapter 13 bankruptcy case is $313. You will probably also have costs for the required credit counseling and debtor education courses. If you hire an attorney there will probably also be attorney fees. Like Chapter 7 cases, attorney fees vary by location and case difficulty. Depending on the case and your local rules, some Chapter 13 attorney fees may be paid through the Chapter 13 plan rather than entirely before the case is filed.
Is Chapter 13 Worth It?
Filing Chapter 13 may be worth considering if it solves a problem that Chapter 7 may not be able to solve. For example, in Chapter 13 you may be able to catch up on missed mortgage or vehicle payments, and protect property that is not exempt in Chapter 7.
What Information Should You Gather Before Choosing Chapter 7 or Chapter 13?
Before deciding on a chapter, it really helps to get a clear picture of your finances. This is the type of information I look at to get a better idea of whether Chapter 7 or Chapter 13 may make more sense for someone:
- Your household income for roughly the last six months
- Your monthly expenses
- The approximate value of your home, vehicles, and other significant property
- The balances owed on secured property (home and vehicles for example)
- Whether you are behind on a mortgage or vehicle
- The types and approximate amounts of your unsecured debts
- If you have recently sold, transferred, or given away any property
- Your goals and what you want to accomplish in bankruptcy
At first you don't necessarily need perfect details before you start comparing your options, but having this information available can make it easier to understand the advantages and potential risks of each chapter.
Final Thoughts: Chapter 7 or Chapter 13?
As you can see from our discussion and use of the chapter 7 vs chapter 13 tool, the chapter that works for you is always going to be based on your specific situation and what your goals are. There is no one-size-fits-all analysis when it comes to chapter 7 vs chapter 13. The best way to get clear answers is to do your research and get good, qualified legal guidance from a bankruptcy lawyer if you're unsure. At the end of the day when it comes to your finances there is a lot at stake.
Legal Disclaimer: USBankruptcyHelp.com is not a law firm and does not provide legal or financial advice. The information on this page is for educational purposes only and is not a substitute for advice from a licensed bankruptcy attorney. Bankruptcy outcomes depend on your individual circumstances, applicable law, local court procedures, and the facts of your case. Using this website does not create an attorney-client relationship.
Explore More Bankruptcy Guides and Tools
Continue your research with these bankruptcy guides, calculators, and decision tools.
Explore Bankruptcy Help by State
Browse our state guides to learn exemptions, means test rules, costs, and local procedures. Use these links to jump between states and compare your options.
- Arizona
- California
- Colorado
- Florida
- Georgia
- Illinois
- Indiana
- Maryland
- Michigan
- Nevada
- New York
- North Carolina
- Ohio
- Oregon
- Pennsylvania
- Tennessee
- Texas
- Virginia
- Wisconsin