New York Bankruptcy Exemptions
New York bankruptcy exemptions can protect your home, car and other property. Check out the exemptions available, their limits, and which protections apply to you.

Which Bankruptcy Exemptions Can You Use in New York?
New York is a Dual Choice Bankruptcy Exemption Jurisdiction
New York is a dual choice bankruptcy exemption jurisdiction. This means that you may use New York bankruptcy exemptions under New York Debtor and Creditor Law § 282 or the federal bankruptcy exemptions under 11 U.S.C. § 522(d). This is the New York exemption scheme. You can only use one or the other. Not both. Check out the video below that explains the dual choice exemption system in New York.
How Do You Know if You Can Use New York's Exemption Scheme?
It's important to understand which exemption laws you can use when you file bankruptcy. Simply being a resident of New York doesn't mean that you automatically get to use New York's exemption laws. New York’s exemption laws generally apply if you were domiciled there throughout the 730 days immediately before filing your bankruptcy case. If you weren't domiciled in one state throughout that period, look at the 180 days immediately before that 730-day period began. The applicable state is the one where you were domiciled throughout those 180 days, or for a longer portion of that period than in any other state.. See 11 U.S.C. § 522(b)(3)(A). If you haven't been domiciled in New York for that amount of time, then you may have to use another state's exemption laws. We understand that the bankruptcy exemption choice rule can seem a little complicated, so we made the video below to help explain how it works.
Find Which State's Exemption Laws Apply to You
If you're not sure which exemptions you can use we created a free Bankruptcy Exemption Law Finder Tool below. Simply enter your information in the fields, and the tool will estimate which state's exemption laws could apply to you. You can save and/or print your results. The tool isn't legal advice, but it is a good starting point. No email address or phone number is required to use it or see your results and we do not store any information entered.
Which Bankruptcy Exemptions Can I Use?
Where you live today does not always determine which bankruptcy exemptions you can use. Enter your domicile history to see which exemption law may apply.
This tool identifies the exemption system you may be eligible to use. It does not determine whether a particular house, vehicle, bank account, or other asset is fully protected.
New York vs. Federal Bankruptcy Exemption Limits
Below are a series of tables with the latest exemptions available to New Yorkers. The tables compare the New York state exemptions vs the federal exemptions so that you can see the difference. We've also added examples of how certain exemptions could be used in the real world. The New York dollar amounts below took effect April 1, 2024. The next adjustment is scheduled for April 1, 2027. The federal amounts apply to cases filed on or after April 1, 2025. Note that the linked statutes may display older base amounts; see the official New York DFS adjustment schedule. Amounts are for one eligible filer unless stated otherwise; joint filers must assess each person's ownership and eligibility.
New York vs. Federal Homestead Bankruptcy Exemptions
A homestead exemption protects the equity you own in your home. Below are the New York homestead exemption rule and amounts versus the federal homestead exemption rules and amount. Note that the New York exemption amounts can depend on where your New York home is located.
| Exemption | New York protection | Federal protection | Legal authority |
|---|---|---|---|
| Homestead | Equity in a house, condo, co-op or mobile home you own and occupy as your principal residence. Limits depend on the county: $204,825: Kings, Queens, New York, Bronx, Richmond, Nassau, Suffolk, Rockland, Westchester and Putnam. $170,700: Dutchess, Albany, Columbia, Orange, Saratoga and Ulster. $102,400: All other New York counties. | Up to $31,575 in your interest in real or personal property used as a residence by you or a dependent, including a qualifying co-op. The same limit applies throughout New York and is shared with any burial-plot exemption below. | |
| Burial ground or burial plot | A family or private burial ground of up to one-quarter acre, with a portion already used for burial. Structures are limited to vaults, other places for depositing the dead, or mortuary monuments. This provision has no stated dollar cap. | Your interest in a burial plot for you or a dependent may be protected within the same $31,575 combined limit used for the residence. This is not an additional $31,575 exemption. | |
| Rent-stabilized lease | Your interest in a rent-stabilized lease is exempt, with no dollar cap stated in this provision. | No rent-stabilized-lease-specific exemption appears in § 522(d). Whether another federal exemption protects the interest requires separate analysis; the New York lease exemption does not carry over when you choose the federal list. |
Example: Protecting Your Home Under New York Exemptions vs Federal Exemptions
Assume that you have a primary residence in Albany County that is worth $300,000, that has a mortgage balance of $250,000, with no other liens, leaving you with $50,000 in equity. Assume also that you have lived in that Albany home for 3 years.
Using New York exemptions: In this case you would probably want to use the New York homestead exemption for Albany, which is $170,700. This would be more than enough to protect your $50,000 in equity. See the county-based homestead rules and the adjusted New York limits for reference.
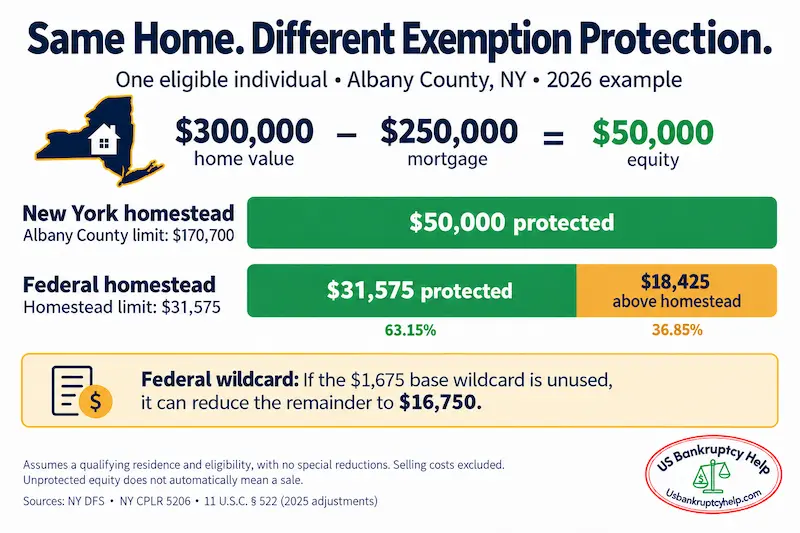
Using federal exemptions: Under the federal bankruptcy exemptions you would be able to use the $31,575 homestead exemption, leaving $18,425 of your home's equity not protected. If you don't use your federal wild card exemption, you could apply the base amount of $1,675 here, reducing your unprotected equity to $16,750.
How the Homestead Exemption Works for Married Joint Filers
Married joint filers can't choose different exemption systems, and each spouse must qualify for the exemptions they claim. So for example, if spouses file a joint bankruptcy case in New York and qualify to use New York exemption laws, one spouse can't use the federal exemptions, while the other uses the New York exemptions. See 11 U.S.C. § 522(b)(1) and § 522(m).
New York vs. Federal Motor Vehicle Exemptions
Both New York and the federal exemptions have specific exemptions for equity in motor vehicles. The amounts are similar; however, the protection for disabled filers is significantly different.
| Exemption | New York protection | Federal protection | Legal authority |
|---|---|---|---|
| One motor vehicle | Up to $5,500 in equity in one motor vehicle. | Up to $5,025 in equity in one motor vehicle. | |
| Vehicle equipped for a disabled debtor | Up to $13,625 in equity in one vehicle equipped for use by a disabled debtor. This higher limit replaces the ordinary $5,500 limit; the two amounts are not added together. | The same $5,025 vehicle exemption applies. Section 522(d)(2) does not provide a higher limit for a vehicle equipped for a disabled debtor. |
Example: Protecting Equity in Your Car Using New York vs Federal Exemptions
Assume that you own a car that is worth $15,000 and owe $8,000 on it, leaving you with $7,000 of equity in the vehicle.
Using the New York motor vehicle exemption of $5,500, $1,500 of your equity would not be covered by it. Using the $5,025 federal motor vehicle exemption $1,975 would not be covered by that motor vehicle exemption. Note that depending on the circumstances, an available wildcard could protect some or all of the difference.
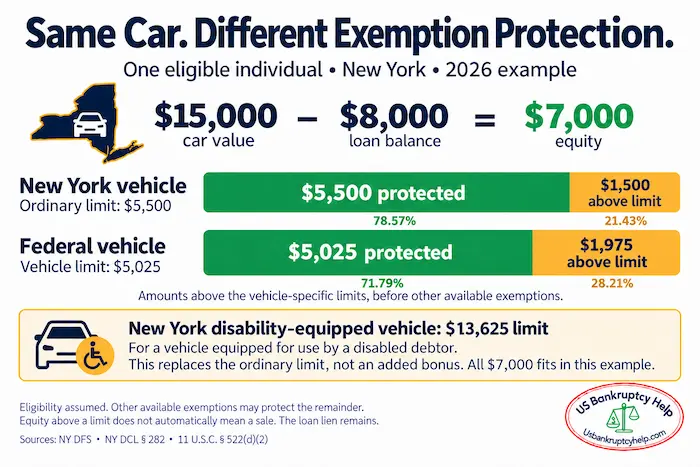
New York does offer a higher limit of $13,625 for vehicles equipped for use by a disabled debtor. This amount is not in addition to the $5,500 limit. In our example above, if the vehicle was equipped for disabled use according to the rules, all of the vehicle's equity would be covered by the New York exemption.
New York vs. Federal Personal Property Exemptions
Both the New York and the federal exemptions protect similar everyday personal property items, but the limits work differently. For example, under New York law, the personal property items in this category share a $13,625 combined limit. Some categories also have smaller limits, which are applied toward the $13,625 total. Please note that the separate disability-related protection under CPLR § 5205(h), shown in the last row, is not subject to this shared limit. See DCL § 283(1).
The household-goods exemption under the federal exemption system protects up to $800 per item and $16,850 total for items held primarily for your personal, family, dependent or household use. Jewelry and tools of the trade have separate federal limits. The table below compares the protections available under the New York and federal exemption systems. See 11 U.S.C. § 522(d)(3), (4), and (6).
| Exemption | New York protection | Federal protection | Legal authority |
|---|---|---|---|
| Clothing, furniture and household essentials | Necessary clothing, furniture, cookware and listed appliances/electronics, including one refrigerator, radio, television, computer with associated equipment and cellphone. | Qualifying clothing, furnishings, appliances and household goods share the federal household limit. | |
| Heating equipment, fuel and sewing machine | Home stoves and heating equipment, necessary fuel for 120 days, and one sewing machine with accessories. | Qualifying household goods or appliances share the household limit. No separate 120-day fuel allowance. | |
| Food | Necessary food already provided for you and your family for 120 days. | No separate 120-day allowance. Any household-goods claim is subject to the household limit. | |
| Religious texts, schoolbooks and family pictures | Religious texts, schoolbooks, family pictures and portraits used by you or your family. | Books and qualifying household goods share the household limit. | |
| Other library books | Up to $675 for other books kept and used in your or your family's library. | Books share the same household limit, not a separate library-books allowance. | |
| Wedding ring | A wedding ring is outside the watch/jewelry/art sublimit, but still counts toward the New York shared cap. | Included in the $2,125 combined jewelry limit, shared with watches and other qualifying jewelry. | |
| Watch and other jewelry | Up to $1,325 combined for a watch, other jewelry and art. The separately listed wedding ring is excluded from this sublimit. | The same $2,125 combined jewelry limit, including any wedding ring claimed under it. | |
| Art | Shares the same $1,325 watch/jewelry/art sublimit above. This is not an additional allowance. | No art-specific exemption. A household-goods claim depends on the artwork and its use and shares the household limit. | |
| Tools of the trade | Up to $4,075 for necessary work tools, professional instruments/books and other qualifying equipment used in your profession or calling. | Up to $3,175 combined for implements, professional books and tools used in your or a dependent's trade. | |
| Domestic animals and their food | Up to $1,325 combined for domestic animals and their necessary food for 120 days. | Qualifying animals share the household limit. No separate 120-day animal- food allowance. | |
| Seat or pew in a place of worship | A seat or pew occupied by you or your family in a place of public worship. | No specifically listed seat-or-pew exemption. | |
| Prescribed health aids | Prescribed health aids count toward the New York shared cap when claimed under § 5205(a)(5). The separate protection below may also apply. | Professionally prescribed health aids for you or a dependent have no stated dollar cap. | |
| Disability equipment and assistance animals | Qualifying medical/dental aids and equipment supporting major life activities or mobility for a person with a permanent disability; qualifying trained assistance animals actually used, with their food. Limited to reasonable needs, but outside the New York shared cap. | Property meeting the professionally prescribed health-aid requirements may receive uncapped protection. Other equipment or animals need a separate applicable exemption. |
Example: The Same Household Property Under Each System
Assume that Bob owns a sofa worth $1,200 and also has $4,800 in other ordinary household furniture and clothing. Each of the other items is worth less than $800. Bob hasn't used any of New York's shared exemption limit on any other property.
Under New York exemptions: All $6,000 of Bob's personal property listed in the example would be covered by the New York exemption $13,625 shared limit.
Using federal exemptions: The household goods exemption would protect $800 of Bob's $1,200 sofa, leaving $400 unprotected. His other $4,800 in household furniture and clothing would be fully protected because each of those items is worth less than $800 and the combined exemption claim stays below the $16,850 aggregate limit. In total, this exemption would protect $5,600 of the $6,000 in property. Bob could also protect the remaining $400 if he has enough federal wildcard exemption available.
New York vs. Federal Wildcard and Cash Exemptions
The New York wildcard exemption protects up to $1,325 in personal property, a bank account or cash if you don't claim a homestead exemption. New York also provides a conditional cash exemption of up to $6,825, which is subject to the conditions below.
The federal wildcard exemption protects up to $1,675 in any property, plus up to $15,800 of unused federal homestead or burial-plot exemptions.
| Exemption | New York protection | Federal protection | Legal authority |
|---|---|---|---|
| Wildcard | Up to $1,325 in personal property, a bank account or cash, if no homestead exemption is claimed. This amount counts toward the $13,625 shared limit. | $1,675 in any property, plus the smaller of $15,800 or your unused § 522(d)(1) residence/burial-plot exemption. The maximum wildcard is $17,475. Homeownership is not required. Claiming part of the residence exemption does not automatically eliminate the wildcard. The $1,675 base remains available even if no § 522(d)(1) amount is unused. | |
| Cash | The lesser of $6,825 or the unused portion of the $13,625 shared limit, after fully using the exemptions subject to that limit as they apply to your property. Count any $1,325 wildcard claimed before calculating the remaining room. You must not elect, claim or otherwise use any exemption under CPLR § 5206. This condition is broader than simply not claiming its homestead exemption. Cash includes U.S. currency and U.S. savings bonds at face value, federal/state/local income-tax refund rights, and deposit accounts at state- or federally chartered depository institutions. | Cash, bank-account balances and tax-refund interests may use the same wildcard allowance above, subject to the amount still available. They share that allowance with any other property claimed under § 522(d)(5). There is no separate additional cash allowance under this provision. |
Example: $5,000 in Cash and No Homestead Exemption
Assume that Bob is eligible to choose New York or federal exemption systems and isn't claiming a homestead exemption. Bob has $5,000 in cash plus $10,000 in other personal property. Bob's other personal property qualifies under New York's shared personal-property allowance, and Bob's fully used the exemptions applicable to it. Bob's $10,000 in claims includes the entire $1,325 wildcard.
Under New York exemptions: Subtracting the $10,000 from the $13,625 aggregate limit leaves Bob $3,625 available. The conditional cash exemption under Debtor and Creditor Law § 283 protects the smaller of that remaining amount or the $6,825 cash ceiling. Here, it covers $3,625 of the $5,000, leaving $1,375 outside this cash exemption unless another protection applies. You cannot add the $1,325 wildcard again because it was already used in the $10,000 total. See the current New York exemption adjustments.
Under federal exemptions: Since Bob isn't using the homestead exemption he will have up to $17,475 of protection available under § 522(d)(5): this includes the $1,675 base wildcard plus up to $15,800 from unused homestead protection. These are the federal amounts effective as of April 1, 2025. With no other claims against that wildcard, it could cover all $15,000 of property and cash in this example, even without using separate personal-property exemptions. It is one shared allowance, not $17,475 for cash plus another $17,475 for other assets.
New York vs. Federal Retirement and Financial Exemptions
The New York and the federal bankruptcy exemption systems protect qualifying retirement accounts and other qualifying financial assets. Some retirement plans stay outside the bankruptcy estate altogether. For example, a qualifying ERISA-covered employer retirement plan can be protected under 11 U.S.C. § 541(c)(2), regardless of whether or not there is a bankruptcy exemption available for it.
| Exemption | New York protection | Federal protection | Legal authority |
|---|---|---|---|
| Qualified retirement accounts | No dollar cap stated in CPLR section 5205(c) for qualifying traditional and Roth IRAs, Keogh plans, covered employer plans and eligible rollovers. Domestic-relations orders, certain recent additions and voidable transfers can affect protection. | Qualifying tax-exempt retirement funds are protected. Ordinary traditional and Roth IRAs generally share a $1,711,975 aggregate cap. SEP/SIMPLE IRAs and specified employer-plan rollover amounts and their earnings are outside that cap; a court may increase it. Qualifying ERISA plan interests may instead be excluded from the estate under section 541(c)(2). | |
| Pension and similar plan payments | The right to qualifying pension, stock-bonus, profit-sharing and similar payments based on illness, disability, death, age or length of service is protected. Certain debtor- or insider-established, age/service-based nonqualified plans are excluded. | The right to qualifying payments on these grounds is protected only to the extent reasonably necessary to support you and your dependents, subject to the statutory insider-plan exception. This is separate from the retirement-funds exemption above. | |
| New York public retirement benefits | Benefits and contribution refunds covered by RSSL section 110 receive statutory protection with no stated dollar cap, subject to applicable exceptions. | The qualifying retirement-fund or payment protections above may apply. Section 522(d) provides no additional exemption simply because the plan is a New York public retirement plan. | |
| New York 529 college savings | $13,625 combined in qualifying New York program accounts you own. Qualifying scholarship accounts and accounts owned by a minor who is also the beneficiary have full protection. This is separate from the personal-property aggregate limit. | Section 541(b)(6) excludes qualifying state 529 program funds from the estate, rather than creating a matching exemption. The beneficiary must be your child, stepchild, grandchild or stepgrandchild in the contribution year, including qualifying adopted/foster relationships. Applicable contribution limits also apply. Less than 365 days before filing: contributions are not excluded under this rule. 365 through 720 days before filing: up to $8,575 per beneficiary across qualifying contributions in that period. More than 720 days before filing: the $8,575 timing cap does not apply; the other conditions still do. | |
| Trusts funded by someone else | Qualifying third-party-funded principal is protected while held in trust. Generally 90% of trust income is protected, subject to the court's reasonable-needs limit. Qualifying retirement trusts have different rules. | A trust interest with an enforceable transfer restriction under applicable nonbankruptcy law may be excluded under section 541(c)(2). Otherwise, no blanket federal trust exemption applies; an available exemption, such as the wildcard, is needed. | |
| Residential rent and utility deposits | Qualifying security deposits for your or your family's residence and covered residential utility services are protected, with no stated dollar cap. | No deposit-specific exemption under section 522(d). Any available federal wildcard may cover your interest in the deposit, using the same wildcard pool as other property. |
Example: Retirement Savings vs. Ordinary Bank Cash
Assume Bob has $100,000 in a qualifying traditional IRA and $5,000 that he set aside for retirement in a savings account. Bob's IRA isn't inherited, meets exemption requirements, and his combined IRA balances are below the federal cap. Bob's savings account contains cash only.
Using New York bankruptcy exemptions: Bob's $100,000 IRA can be protected under New York's retirement-account exemption in CPLR § 5205(c). Bob wouldn't need to use his cash or wildcard allowance to protect this IRA.
Using federal bankruptcy exemptions: Bob's $100,000 IRA would be protected under 11 U.S.C. § 522(d)(12).
Bob's $5,000 savings account: Bob may have set this money aside for retirement, but that doesn't mean that Bob's account is protected. If Bob wants to protect this money he will need to use an available cash or wildcard exemption.
New York vs. Federal Insurance and Annuity Exemptions
If you file bankruptcy and have an annuity or insurance policy you have to pay attention to all the details of these assets. For example, an insurance policy, its cash value and a payment from it could be treated differently in your case. Ownership, policy beneficiary designations, and payment terms can affect whether an exemption applies. These details are easy to overlook, so keep them in mind as you compare New York and federal protections below.
| Exemption | New York protection | Federal protection | Legal authority |
|---|---|---|---|
| Life insurance policies and cash value | Qualifying cash value and other policy proceeds may be protected without a stated dollar cap. Ownership, insured/beneficiary relationships and whose creditors are involved control. | Policy: An unmatured life insurance contract you own is protected, except credit life insurance. Value: Up to $16,850 aggregate in accrued dividends, interest and loan value in qualifying unmatured policies you own insuring you or someone of whom you are a dependent, reduced by applicable section 542(d) transfers. | |
| Life insurance death benefits | Protection against the insured's or purchaser's creditors does not automatically protect a beneficiary from their own creditors. A spouse who obtained insurance on the other spouse's life for their own benefit has express protection against their own creditors. | Your right to payment, or traceable proceeds, is protected if you were the insured's dependent at death, but only as reasonably necessary to support you and your dependents. | |
| Accelerated life insurance benefits | Qualifying accelerated death benefits and special surrender payments are protected for the policyowner. The right to accelerate benefits or enter a qualifying viatical settlement is also protected. | No separate exemption merely because a benefit is accelerated. The payment must satisfy another applicable exemption; the death-benefit rule is not an automatic match. | |
| Private disability insurance | DCL section 282(2)(c) separately protects your right to receive, or interest in, qualifying disability or illness benefits, with no stated dollar cap. Under Insurance Law section 3212(c), disability-income protection against post-disability debts excludes debts for necessaries and otherwise is limited to $400 per month. This is not a blanket bankruptcy cap. | Your right to receive qualifying disability or illness benefits has no stated dollar cap. Already-received funds require separate review. | |
| Annuities | Qualifying rights of the annuitant who paid for the contract, and certain beneficiary payments, are protected. Courts may direct part of payments to creditors after considering family needs. Covered contracts initially purchased within six months before filing share the $13,625 aggregate with covered personal property. Section 283(1)'s specific tax-code and settlement-option exceptions apply. This is not an additional annuity allowance. | Qualifying payments based on illness, disability, death, age or length of service are protected only as reasonably necessary for support, subject to the insider-plan exception. Qualifying retirement annuities may instead use the retirement-funds protections discussed above. |
Example: $20,000 in Whole-Life Insurance Cash Value
Suppose you are filing individually and can choose either exemption system. Years ago, you bought a whole-life policy on your own life and named your spouse as beneficiary. You still own the policy, it has not matured, and its cash surrender and loan values are both $20,000. Assume there are no policy loans, fraudulent premium payments or transfers, or reductions under section 542(d).
Under New York exemptions: The full $20,000 can be protected from your creditors under Insurance Law § 3212(a)(1) and (b)(1), incorporated into the bankruptcy exemptions by Debtor and Creditor Law § 282. The protection covers cash value in this arrangement without a stated dollar cap. Who obtained the policy, whose life it insures, and who receives the benefit matter.
Under federal exemptions: Section 522(d)(8) protects up to $16,850 under the amounts effective April 1, 2025, assuming you have no other policy values using that allowance. That leaves $3,150 outside this exemption. An available federal wildcard could cover the difference, but it would leave less wildcard protection for your other assets.
The separate federal exemption for the unmatured insurance contract itself does not make all of its cash value exempt. This example concerns a living policyholder's cash value, not a beneficiary's death-benefit payment or an annuity. Those require the separate analysis described above.
Federal law includes a spouse as a dependent even without financial dependence under section 522(a)(1). New York's protections remain subject to the fraud-related exceptions in Insurance Law section 3212(e).
New York vs. Federal Income and Benefit Exemptions
Some income and benefits like wages, Social Security, disability, and unemployment can be protected by New York and federal bankruptcy exemptions. The table below compares the protections available under New York and federal law.
| Exemption | New York protection | Federal protection | Legal authority |
|---|---|---|---|
| Wages and earnings | Generally 90% of qualifying wages earned within 60 days before filing, subject to reasonable support needs. Deposited wages must remain identifiable; not every bank balance qualifies. | No wage-specific exemption for prefiling earnings under section 522(d). An available wildcard may apply. In Chapter 7, wages you earn from work performed after you file generally stay outside the bankruptcy estate, so you do not need an exemption to protect them. In Chapter 13, those earnings generally become part of the bankruptcy estate and help fund your repayment plan. | |
| Social Security and local public assistance | Your right to receive, or interest in, qualifying benefits is protected, with no stated dollar cap. Social Security also has the independent federal protection described alongside. | The right to receive qualifying benefits has no stated dollar cap under section 522(d)(10)(A). Social Security, including SSI, also has independent federal protection for identifiable paid benefits and qualifying future benefits regardless of exemption choice, subject to statutory exceptions. | |
| Unemployment benefits | Your right to receive, or interest in, qualifying unemployment benefits is protected, with no stated dollar cap. | Your right to receive qualifying unemployment benefits is protected, with no stated dollar cap. | |
| Veterans' benefits | Your right to receive, or interest in, qualifying veterans' benefits is protected. On the state/nonbankruptcy exemption track, section 5301 also protects qualifying VA payments before and after receipt, subject to statutory exceptions and identification of the funds. | Your right to receive qualifying veterans' benefits is protected, with no stated dollar cap. Already-paid funds need separate review; section 5301 is not automatically available with a section 522(d) election. | |
| Disability and illness benefits | Your right to receive, or interest in, qualifying disability or illness benefits is protected, with no stated dollar cap under this bankruptcy provision. | Your right to receive qualifying disability or illness benefits is protected, with no stated dollar cap. | |
| Workers' compensation | Qualifying workers' compensation disability benefits can be protected under DCL section 282(2)(c). Section 33 separately protects covered compensation from creditor process, with support-enforcement exceptions. Already-received settlements require careful review. | Qualifying disability-benefit rights may fit section 522(d)(10)(C). Treatment of an already-paid settlement depends on the payment's nature and timing, not merely its workers' compensation label. | |
| Alimony, support and separate maintenance | Your qualifying right to receive, or interest in, these payments is protected only to the extent reasonably necessary to support you and your dependents. | Your right to receive these payments is protected only to the extent reasonably necessary to support you and your dependents. | |
| Military pay, awards and service equipment | The statute protects specified military pay, pensions, service awards, uniforms and equipment. Its protection does not cover all military-related assets, and family-support exceptions apply. | No matching blanket military-pay or equipment exemption. Applicable benefit, pension, personal-property or wildcard protections may cover particular assets. | |
| Farm milk-sale proceeds | 90% of qualifying amounts owed or becoming due for milk produced on your farm and delivered to a licensed milk dealer. | No milk-proceeds exemption under section 522(d). An available wildcard may apply. |
Example: Social Security Deposits Versus Ordinary Savings
Assume that Bob files Chapter 7 with $4,000 in an account containing only traceable Social Security retirement benefits and $2,000 in a separate savings account. Assume that the Social Security benefit money remains available for withdrawal and no statutory exception applies.
Bob's $4,000 in Social Security benefits would be protected by 42 U.S.C. § 407 whether he chooses New York or federal bankruptcy exemptions. Depositing Social Security benefits doesn't end that protection. In Philpott v. Essex County Welfare Board, the Supreme Court protected deposited benefits that remained readily withdrawable.
To protect the $2,000 in savings, Bob will need to use another exemption like a cash or wildcard exemption.
New York vs. Federal Exemptions for Claims and Awards
New York and federal exemptions could protect your legal claim or settlement award. The table below compares New York and federal protections for personal injuries, wrongful death, lost future earnings, crime-victim compensation and damage to exempt personal property.
| Exemption | New York protection | Federal protection | Legal authority |
|---|---|---|---|
| Personal bodily-injury payments | Up to $10,250 for qualifying bodily injury to you or someone of whom you are a dependent. This specific exemption excludes pain and suffering and compensation for actual pecuniary (financial) loss. | Up to $31,575 for qualifying bodily injury to you or someone of whom you are a dependent. This specific exemption also excludes pain and suffering and compensation for actual pecuniary loss. | |
| Wrongful-death payments | Qualifying payments for the wrongful death of someone of whom you were a dependent, only to the extent reasonably necessary to support you and your dependents. | Qualifying payments for the wrongful death of someone of whom you were a dependent, only to the extent reasonably necessary to support you and your dependents. | |
| Compensation for future lost earnings | Qualifying compensation for your lost future earnings, or those of someone of whom you are or were a dependent, only to the extent reasonably necessary to support you and your dependents. | Qualifying compensation for your lost future earnings, or those of someone of whom you are or were a dependent, only to the extent reasonably necessary to support you and your dependents. | |
| Crime-victim compensation | Your right to an award under a qualifying crime-victim reparation law, and property traceable to that award, are protected with no stated dollar cap. | Your right to an award under a qualifying crime-victim reparation law, and property traceable to that award, are protected with no stated dollar cap. | |
| Damage to exempt personal property | A qualifying claim for taking or injuring personal property exempt under CPLR section 5205 is protected. A resulting money judgment and its proceeds are protected for one year after collection. | No matching general exemption for property-damage claims under section 522(d). An available wildcard may cover the claim or proceeds; other protection depends on the asset and circumstances. |
Example: Protecting a Bodily-Injury Payment
Assume that Bob files Chapter 7 in 2026 and still holds $20,000 from a settlement he got as a result of bodily injury. This $20,000 qualifies for the bodily injury exemption, does not include pain and suffering, and does not include compensation for financial loss. The funds can be traced to the actual settlement payment Bob received.
New York exemptions would protect $10,250 of Bob's settlement leaving $9,750 unprotected by the New York exemption. The federal exemption would protect the full $20,000 as it is under the federal $31,575 bodily-injury limit.
Get Bankruptcy Help for Your City in New York State
We’ve compiled helpful resources for individuals in major cities across New York. Click below for localized information:
Explore Bankruptcy Help by State
Browse our state guides to learn exemptions, means test rules, costs, and local procedures. Use these links to jump between states and compare your options.
- Arizona
- California
- Colorado
- Florida
- Georgia
- Illinois
- Indiana
- Maryland
- Michigan
- Nevada
- New York
- North Carolina
- Ohio
- Oregon
- Pennsylvania
- Tennessee
- Texas
- Virginia
- Wisconsin