Understanding the Chapter 13 Bankruptcy Vehicle Cram Down
This guide will help you understand how to use chapter 13 bankruptcy to reduce your car loan and get a fresh start.

How This Article Was Reviewed▾
How We Review This Educational Content▾
Why You Can Trust This Page▾
What Is a Vehicle Cram Down in Chapter 13 Bankruptcy?
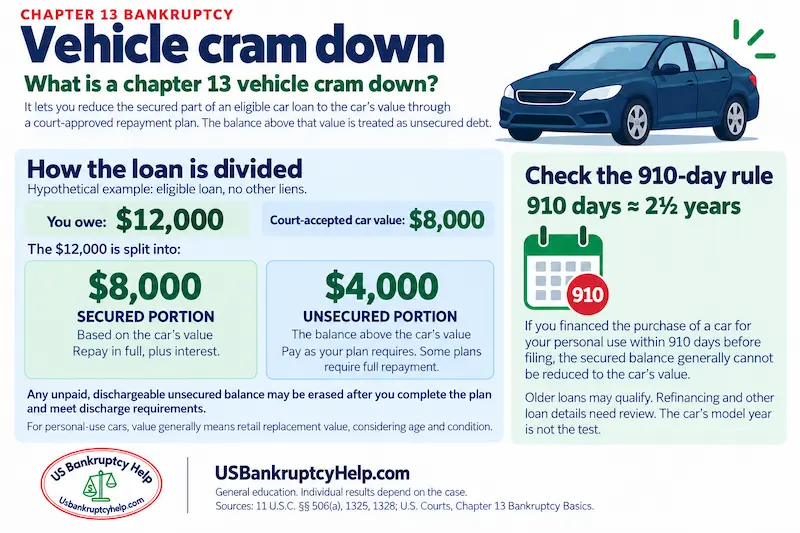
A vehicle cram down allows you to reduce the secured portion of an eligible car loan to the vehicle's value through a chapter 13 repayment plan. The balance above that value becomes unsecured debt, which may receive only partial payment through the plan. This division of the lender's claim is authorized by 11 U.S.C. § 506(a), subject to restrictions discussed below.
This can help when you need a reliable car but owe substantially more than it is worth. The important questions are whether your loan qualifies, what value the court will accept, and whether you can afford the full chapter 13 plan payment.
How Does a Vehicle Cram Down Work?
Hypothetical example:Assume you owe $12,000 on a car loan that qualifies for a cram down. The court accepts an $8,000 value for the vehicle, and there are no other liens on it. The lender's claim would be divided as follows:
| Part of the claim | Amount |
|---|---|
| Secured portion, based on the car's value | $8,000 |
| Remaining unsecured portion | $4,000 |
The plan would generally pay the $8,000 secured portion in full with interest. The $4,000 unsecured portion would receive the treatment required for that claim under your plan. If, for illustration, it received a 10% distribution, the lender would receive $400 on that portion. The remaining $3,600 could be discharged after you complete the plan and satisfy the discharge requirements, assuming the debt is dischargeable. See 11 U.S.C. § 1328.
The 10% figure is only an assumption for this example. Your plan may require a different distribution, including full payment of unsecured claims. The $4,000 difference between the loan balance and vehicle value is therefore not automatically $4,000 in savings.
Which Car Loans Qualify? Understanding the 910-Day Rule
The main restriction applies when all three of these conditions are met:
- The lender has a purchase-money security interest, generally meaning its lien secures financing used to buy the vehicle.
- You incurred the debt within the 910 days before filing, roughly two and a half years.
- You acquired the vehicle for your personal use.
When this restriction applies, you generally cannot force the lender to accept a secured claim reduced to the car's value. To keep the vehicle over the lender's objection, the plan generally must provide for payment of its full allowed claim with appropriate interest. The restriction appears in the paragraph following 11 U.S.C. § 1325(a)(9).
A loan secured by a car you already owned may fall outside this purchase-money restriction. Refinancing, business use, or debt rolled into the financing from a previous vehicle requires closer review of the contract, applicable state law, and controlling court decisions. The age of the car alone does not answer whether the loan qualifies.
How Is the Car's Value Determined?
For a personal-use vehicle, bankruptcy law generally uses replacement value: what a retail seller would charge for a comparable vehicle, considering its age and condition. That is different from simply choosing a trade-in offer or auction price. The governing standard is in 11 U.S.C. § 506(a)(2).
As a practical matter, support your proposed value with information about the actual car. Mileage, accident damage, mechanical problems, photographs, repair estimates, and comparable vehicles can help explain why a general pricing guide does or does not fit. A vehicle with a failing transmission should not be presented as though it were in excellent condition.
Can Chapter 13 Change the Interest Rate or Repayment Period?
Even when the 910-day rule prevents a reduction in the secured balance, chapter 13 may still allow changes to the interest rate and payment schedule. A plan can generally modify car-loan terms and spread repayment over its permitted duration, usually three to five years. It does not create a new seven-year repayment period. See 11 U.S.C. § 1322(b)(2) and (d).
Under the formula approach described in the Supreme Court's decision in Till v. SCS Credit Corp., the interest calculation starts with the prime rate and adds an adjustment for repayment risk. The appropriate rate depends on the circumstances. A borrower with a high contract rate may benefit, while someone with an unusually low rate should not assume the bankruptcy rate will be lower.
Will a Cram Down Lower My Chapter 13 Payment?
It may, but reducing the secured car debt does not necessarily reduce your total plan payment by the same amount. The plan must also account for other required payments, attorney and trustee fees, and the amount unsecured creditors must receive based on your income and property. The U.S. Courts' explanation of chapter 13 plan requirements describes these competing obligations.
The practical consequence is that money freed up by reducing the car claim may need to go to other creditors. Before treating a cram down as monthly savings, ask for a calculation of the entire plan. Also budget for insurance, maintenance, and repairs. Keeping the loan affordable will not solve the transportation problem if the car cannot reliably get you to work.
What Must I Do to Keep the Car?
Keeping the vehicle requires a workable plan and continued compliance with its terms. A proposed cram down does not become permanent simply because you file the case.
- Propose supportable loan terms. Identify the balance, vehicle value, interest rate, and payment schedule. The lender may dispute your valuation or proposed treatment, and the court must approve a plan that meets the legal requirements.
- Start the required payments before confirmation. Plan payments generally begin within 30 days after filing, even if the court has not yet approved the plan. Confirm how any required payments protecting the car lender before confirmation will be handled under the applicable court procedures. See 11 U.S.C. § 1326(a).
- Maintain payments and required insurance. Tell your attorney promptly if your income drops, insurance lapses, or a major repair threatens your ability to pay. Those problems need attention before they jeopardize the plan or the vehicle.
Under the usual cram down rules, the lender retains its lien until the underlying debt is paid under nonbankruptcy law or you receive a discharge, whichever happens first. If the case is dismissed or converted before plan completion, the lien remains to the extent recognized by applicable nonbankruptcy law. See 11 U.S.C. § 1325(a)(5)(B)(i).
What If the Car Is Jointly Owned or Someone Co-Signed?
Start by checking the title and loan documents. A person listed as an owner is not necessarily a borrower, and a co-signer does not necessarily own the car. Your attorney needs to determine who owns the vehicle, who owes the debt, and whose ownership interest secures the loan.
Chapter 13's co-debtor stay can temporarily protect an individual who shares liability for a consumer debt or has pledged property to secure it. That protection has exceptions. For example, a creditor can obtain relief to pursue a co-signer to the extent your plan does not propose to pay the claim. See 11 U.S.C. § 1301.
Your discharge also generally does not erase a co-signer's liability under 11 U.S.C. § 524(e). If protecting a family member who co-signed is part of your goal, ask what the lender could still collect from that person under the proposed plan and after your case ends.
What Should I Bring to an Attorney to Evaluate a Cram Down?
Bring the purchase contract, any refinancing documents, your latest loan statement, the vehicle title, and information supporting the car's condition and value. Include the remaining loan term and any missed payments.
Ask the attorney to compare the proposed car-loan treatment with the cost of the full chapter 13 plan. The useful result is a payment arrangement you can sustain while keeping transportation you can depend on.
Explore Bankruptcy Help by State
Browse our state guides to learn exemptions, means test rules, costs, and local procedures. Use these links to jump between states and compare your options.
- Arizona
- California
- Colorado
- Florida
- Georgia
- Illinois
- Indiana
- Maryland
- Michigan
- Nevada
- New York
- North Carolina
- Ohio
- Oregon
- Pennsylvania
- Tennessee
- Texas
- Virginia
- Wisconsin